Three different numbers for the same ring
Insurance value, market value and probate value are three different figures for one piece of jewellery. All three can be right at the same time. Using the wrong one costs people real money.
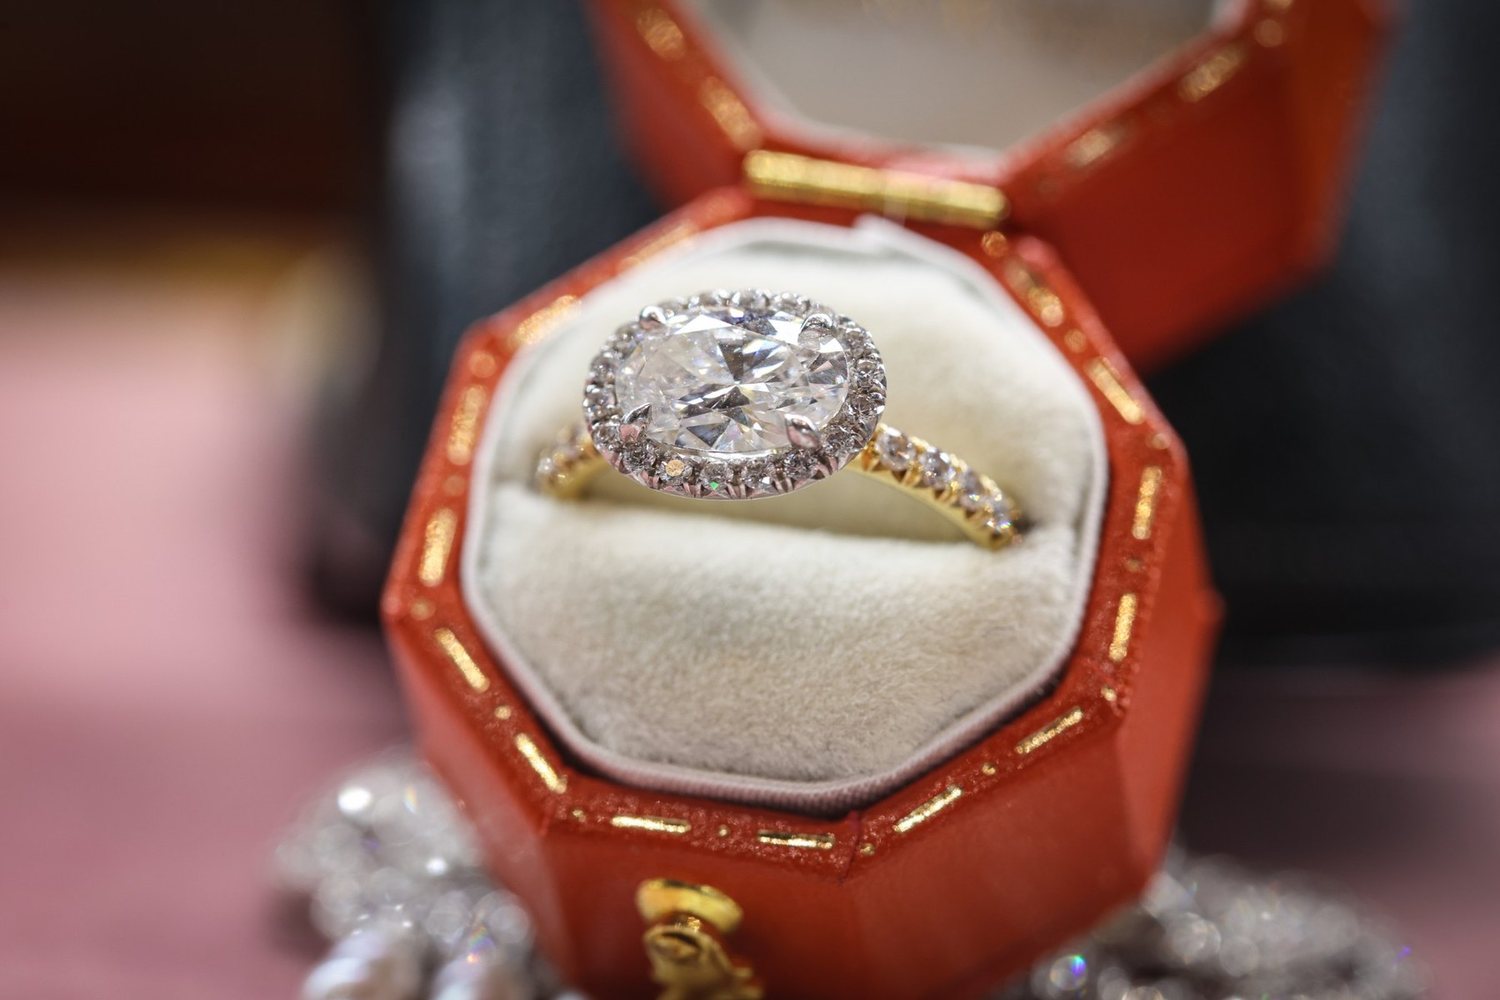
A woman rang me last year, upset. Her mother's ring had been valued at €6,000 for insurance in 2011. The auction house had just offered her €1,900. She wanted to know which one of us was lying.
Neither of us. They are answers to two completely different questions, and there is a third question underneath them both.
Insurance value
This is a replacement figure. It answers: if this piece were stolen from your hotel room tomorrow, what would it cost to go out and buy the nearest equivalent, at retail, from a shop, today.
It is the highest of the three numbers, and it is meant to be. A retail price carries the shop's rent, its staff, its stock sitting in a window for a year, its guarantee and its margin. You are not being overcharged. You are buying from a shop rather than from a dealer's back pocket.
This is the number your insurer wants, and the only one they will act on.
Market value
This answers a different question: if you sold this today, what would you actually be handed.
Whoever buys it has to sell it again. A dealer needs margin. An auction house takes commission from both sides, and a saleroom on a wet Tuesday in February is a lottery. So this figure is typically a fraction of the insurance figure, and for ordinary modern pieces it can be a small fraction.
That gap is the single most upsetting thing in my job to explain, and it is not a scandal. It is the difference between the price in a shop window and the price someone will pay you in cash.
Probate value
This is market value, frozen at a particular moment: the date of death.
It is the figure the estate is assessed on, so it matters to Revenue and it matters to anyone inheriting. It is not what the ring would fetch today, and it is not what it would cost to replace. It is what it was worth, on the open market, on that date.
This is where I see the most expensive mistakes.
An estate valued off an old insurance certificate can be assessed on a figure several times what the jewellery is actually worth.
If a family hands in an insurance valuation because it is the only piece of paper in the box, the estate can be assessed on a number that bears no relation to what the jewellery would ever sell for. Tax gets paid on money nobody will ever see.
It happens the other way too. Someone uses a probate figure to insure a ring they have inherited, and then discovers after a burglary that they are covered for a third of what replacing it costs.
So which do you need
Tell whoever you commission what the valuation is for, before they start. A valuation written for insurance and a valuation written for probate are different documents, not the same document with a different figure on the front.
If the piece is going to be insured, you want a replacement valuation.
If somebody has died, you want a probate valuation at the date of death, set out clearly enough that a solicitor can file it and nobody has to ring you about it later.
If you are dividing things between family, you want market value, because that is the only figure that is fair when one of you takes the ring and the other takes the equivalent in cash.
And if you are just curious what something is worth, say that. It is a shorter conversation and it costs you less.
Colin Weldon · GIA Graduate Gemologist · Dublin